Behavioural finance · Educational
Outside View vs Inside View: Kahneman & Lovallo’s Reference-Class Forecasting Discipline
If you ask an Indian retail investor, “What return will your favourite small-cap stock deliver over the next five years?” you will almost always get a confident, story-driven answer: “The promoter is honest, the order book is strong, the sector is booming — this is at least a 5x.” What you will almost never hear is the response that Daniel Kahneman and Dan Lovallo argued every serious decision-maker should give first: “Let me look at the base rate. What happens to small-cap stocks like this one, on average, over five-year holding periods?” That single shift — from Inside View to Outside View — is, in my experience, the most powerful behavioural upgrade an Indian long-term investor can make.
The Inside View vs the Outside View — What Kahneman and Lovallo Actually Said
The distinction was formalised by Daniel Kahneman and Dan Lovallo in their 1993 Management Science paper “Timid Choices and Bold Forecasts” and revisited at length in Kahneman’s 2011 book Thinking, Fast and Slow (Chapter 23, “The Outside View”). Their definitions are precise:
The Inside View is what happens by default. You look at the specific case in front of you — this stock, this promoter, this product, this story — and forecast its outcome from its unique features. You build a narrative. You notice strengths. You imagine the path to success. The Inside View feels intelligent because it engages with detail. It is also, almost without exception, hopelessly optimistic.
The Outside View deliberately ignores the unique features of your case. Instead, you ask: “What is the appropriate reference class for this decision? What has happened, on average, to similar cases in the past?” You then anchor your forecast on that base rate, and adjust only modestly for genuine differences. Kahneman called this reference-class forecasting, and described it as “the single most important piece of advice regarding how to increase accuracy in forecasting through improved methods.”
The reason the Outside View works is mathematical, not philosophical. Most decisions are not unique. They are members of a population of similar decisions. The base rate of that population is the most reliable predictor available, because it averages out the idiosyncratic noise that fools the Inside View into seeing patterns that are not there.
The Underlying Psychology — Why the Inside View Is Default Mode
Three cognitive forces conspire to make the Inside View feel natural and the Outside View feel artificial:
1. WYSIATI — What You See Is All There Is. Kahneman’s shorthand for the System 1 tendency to build coherent stories out of whatever information is at hand, and to be confident in those stories regardless of whether anything important has been left out. When you research a stock, the brochure-grade information is vivid and present; the population of similar stocks that have already failed is invisible.
2. The Planning Fallacy. Documented across hundreds of studies, the planning fallacy is the empirical observation that people systematically underestimate the time, cost, and difficulty of completing tasks — even when they have completed similar tasks before. The same fallacy applies to investment theses: investors underestimate the time required for a thesis to play out and overestimate the magnitude of the eventual return.
3. The illusion of skill. The Inside View flatters us. It says: “You have done the research. You understand this case. You have an edge.” The Outside View is humbling. It says: “You are one of 4.2 crore Indian retail investors. The base rate of small-cap five-year outperformance, after costs, is what it is, and your stock is not exempt.”
How Inside-View Thinking Manifests in Indian Retail Investor Behaviour
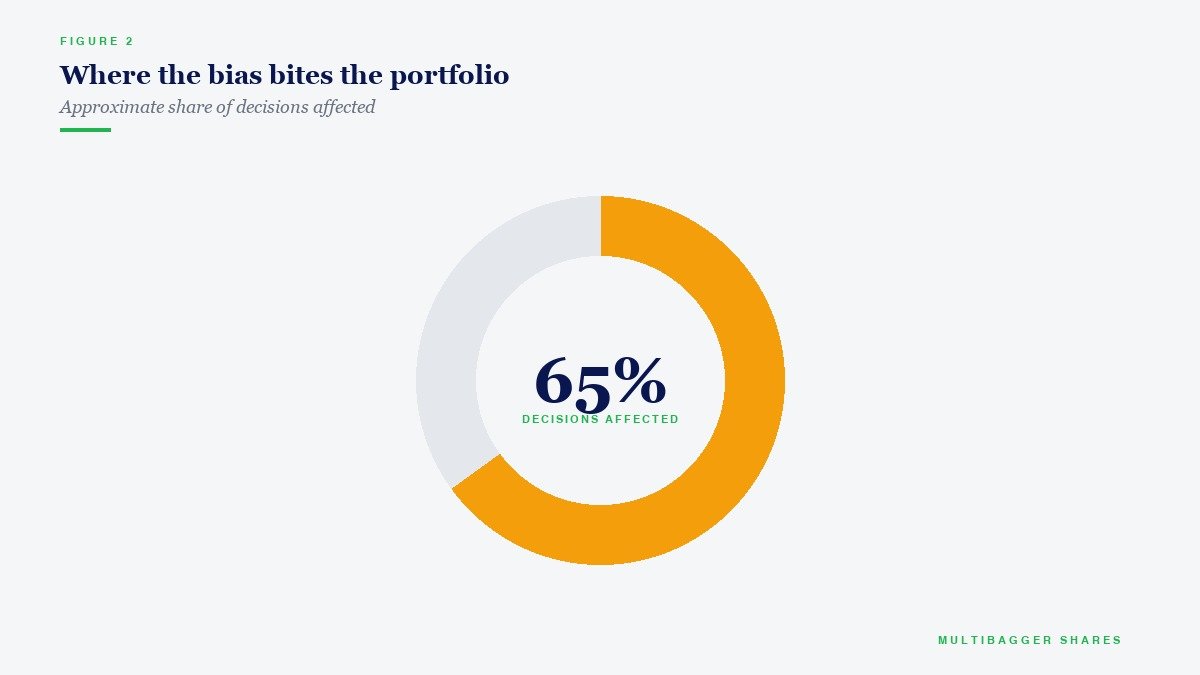
The data is overwhelming. SEBI’s 2024 study of the equity Futures & Options segment found that 93% of individual traders incurred net losses over FY22–FY24, with aggregate net losses of approximately ₹1.81 lakh crore. Every one of those traders, beforehand, had an Inside View — a setup, a chart pattern, a tip, a conviction. None of them began with the Outside View question: “What is the historical base rate of profitability for retail F&O traders in India?” The answer to that question, available from SEBI’s 2019 study and confirmed in 2024, was already ~89–93% loss-making. The Outside View would have ended the discussion.
The same pattern repeats outside derivatives. NSE’s annual reports show that the median Indian demat account holder churns through equity holdings with a holding period of well under 18 months — far below the 5- to 10-year horizons over which equity premiums historically materialise. AMFI data shows that SIP discontinuation rates spike to 60%+ in months following major drawdowns, even though the Outside View on Indian equity markets — 30+ years of post-liberalisation data — shows that drawdowns are followed, on average, by recoveries within 18–30 months.
Prof. V. Ravi Anshuman of IIM Bangalore has published extensively on Indian retail investor behaviour, documenting that the typical retail participant trades far more frequently than is rationally justified, exhibits strong recency bias in stock selection, and consistently overweights idiosyncratic stories at the expense of base-rate evidence. The picture, in short, is a population of investors who almost never consult the reference class.
The Anti-Inside-View Counter-Measure Checklist
Reference-class forecasting is a discipline, not an attitude. Before any major position is sized, the serious Indian long-term investor should run through a structured checklist. The version I use, adapted from Kahneman, Lovallo, and the work of Bent Flyvbjerg on infrastructure-megaproject forecasting, runs as follows:
- Define the reference class precisely. “Indian listed small-cap manufacturers with ROCE >15% and net debt-to-equity <0.10” is a reference class. “Multibagger stocks” is not.
- Find the distribution of outcomes for that class. What is the median 5-year CAGR? The 25th percentile? The 75th percentile? The probability of negative real returns over 5 years?
- Place an anchoring estimate at the median. Begin every forecast at the historical median of the reference class.
- Adjust only on robust, durable differences. A management track record built over decades, a structurally low-debt balance sheet, a high CFO-to-OP conversion ratio — these are durable. A “great quarter” or a “new product launch” is not.
- Force yourself to write down the base rate before any narrative. The act of recording the Outside View first — in a decision journal — is, in my experience, the single most effective behavioural intervention available to an Indian retail investor.
- Run a pre-mortem on the residual. If the Inside View says “5x in five years” and the Outside View says “1.6x in five years”, what would have to be true for your forecast to be right and the base rate wrong? If you cannot articulate it crisply, default to the base rate.
How Graham, Buffett, Munger and Klarman Used the Outside View Decades Before Kahneman Named It
The Outside View predates Kahneman by half a century in value-investing practice. Benjamin Graham’s Security Analysis (1934) is, in essence, an Outside-View manual: every multiple, every margin-of-safety threshold, every working-capital test was a base-rate constraint imposed on the optimistic Inside-View narratives that promoters and brokers tell. Warren Buffett’s frequent reference to the “institutional imperative” — the tendency for management teams to mimic peers — is itself an Outside-View observation. Charlie Munger’s habit of asking “What is the base rate of success for this kind of acquisition?” before approving any Berkshire deal is reference-class forecasting in its purest form. And Seth Klarman’s Margin of Safety (1991) is built around the recognition that Inside-View enthusiasm systematically destroys capital, and that the Outside View — price discipline anchored on conservative historical norms — is the only durable defence.
Key Takeaways
- Always start with the Outside View. Before researching any individual stock, define the reference class and write down its historical base-rate distribution of 5-year and 10-year outcomes.
- Anchor on the median, adjust modestly. Begin every forecast at the median of the reference class. Adjust only on durable structural differences — not stories.
- Use a decision journal to enforce the discipline. Recording the Outside View before the Inside View is the single most cost-effective behavioural intervention available to retail investors.
- Indian retail data is unforgiving of Inside-View thinking. SEBI’s 2024 F&O study found ~93% of individual traders lost money, with aggregate net losses of approximately ₹1.81 lakh crore over FY22–FY24 — a base rate every prospective F&O participant should consult first.
- The Outside View is humbling, and that is the point. Most investment decisions are not unique. The base rate of similar decisions is the best forecast you have. Use it.
Educational content. This article is for education only. It is not a research report and not a recommendation to buy, sell or hold any security, and it does not take your personal circumstances into account. The securities quoted are for illustration only and are not recommendatory.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
Registration granted by SEBI, enlistment as RA with Exchange and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.

Manish GoelChartered Accountant and SEBI Registered Research Analyst (INH100004775). Writes about business quality, valuation and investor behaviour. About